Lifestyle
Displaced From His Job Before 62 With No Savings, He Filed for Social Security. Then He Made Peace With It: “I’m Not Going to Have a Lavish House”
By Curtis Jones · November 7, 2026
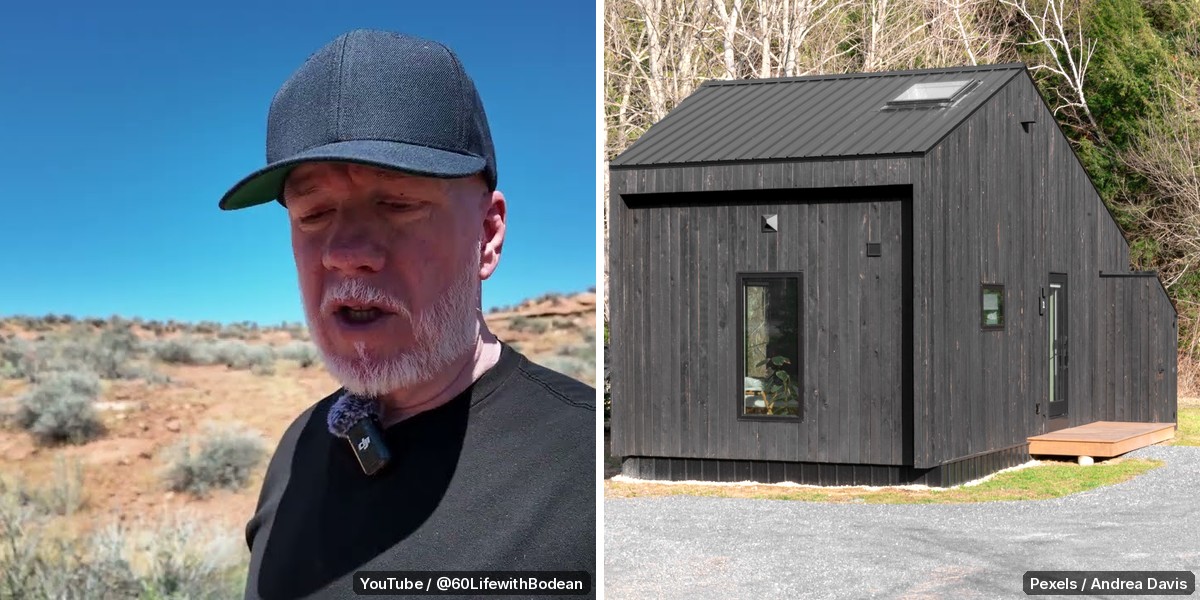
He did not plan to retire when he did. A corporate downsizing made the decision for him.
“I retired with nothing. Nothing in savings, no 401k,” Bodean says at the top of an April video on his channel, 60+ Life with Bodean (@60LifewithBodean). In his telling, he was let go from a management job he liked, a few years before he had planned to stop working. His savings ran out while he looked for something new. “I wasn’t 62 yet,” he says. He was a couple of months short.
He lays out what happened next in his video on YouTube.
He says he could not find a new position, so he filed for Social Security as early as he could. The first 60 days of waiting were panic mode, he says, and after he filed it took more than another 60 days. He called the agency and told them he was in hardship. “Losing my house,” he says, “and I was.” He admits he is a little embarrassed to say it. He says the agency moved quickly once he called, and the check finally came. His wife went back to work, and her paycheck helped them get through.
The second beat is about adjusting rather than escaping. Bodean says the couple will be leaving their home within 30 days for a smaller place that costs less than half as much. They are cutting down to one vehicle. His wife plans to retire in eight to nine months, and for now her income is going toward paying off the rest of their debt. “I’m not going to have a lavish house,” he says. “I’m going to have a tiny home, most likely.”
He says he still feels free, and he talks about his relationships with family and friends as the thing that keeps him going. He hopes the smaller home will leave room to visit their kids, who live in different states.
The rules he ran into are worth knowing. The Social Security Administration says you can start retirement benefits as early as 62, but they are reduced a small percentage for each month before your full retirement age. For people born in 1960 or later, full retirement age is 67, and a benefit started at 62 is reduced by about 30%. SSA also notes that you must be at least 62 for the entire month to receive benefits. For context, SSA’s monthly statistical snapshot puts the average monthly benefit for retired workers at $2,088.79 in September 2026.
If you are facing a sudden job loss before full retirement age, a few steps can help you think it through:
Check your own numbers first. SSA’s early-retirement chart shows how the reduction grows the earlier you start, and the gap between 62 and 67 can be large.
Call early if you are in trouble. Bodean says the agency helped faster once he explained he was about to lose his house.
Count every income source. His wife’s return to work bought them time. Part-time work, a spouse’s pay, or severance can change the math.
Look hard at housing. For Bodean, moving to a cheaper home was the biggest single change.
Get advice before you file. A call to SSA or a talk with a financial adviser can help you weigh the tradeoff before you decide.
Bodean is not selling a plan. He calls retirement on Social Security alone different than he expected, and he still says he is enjoying it. He tells viewers in the same spot not to panic and to make one adjustment at a time.
This article is for general information and is not financial or legal advice. This article was produced with the assistance of AI and fact-checked against the sources cited by LightWave Reports.